How to Build Business Credit in Minnesota: Lessons From the 2026 Hennepin County Small Business Networking Event
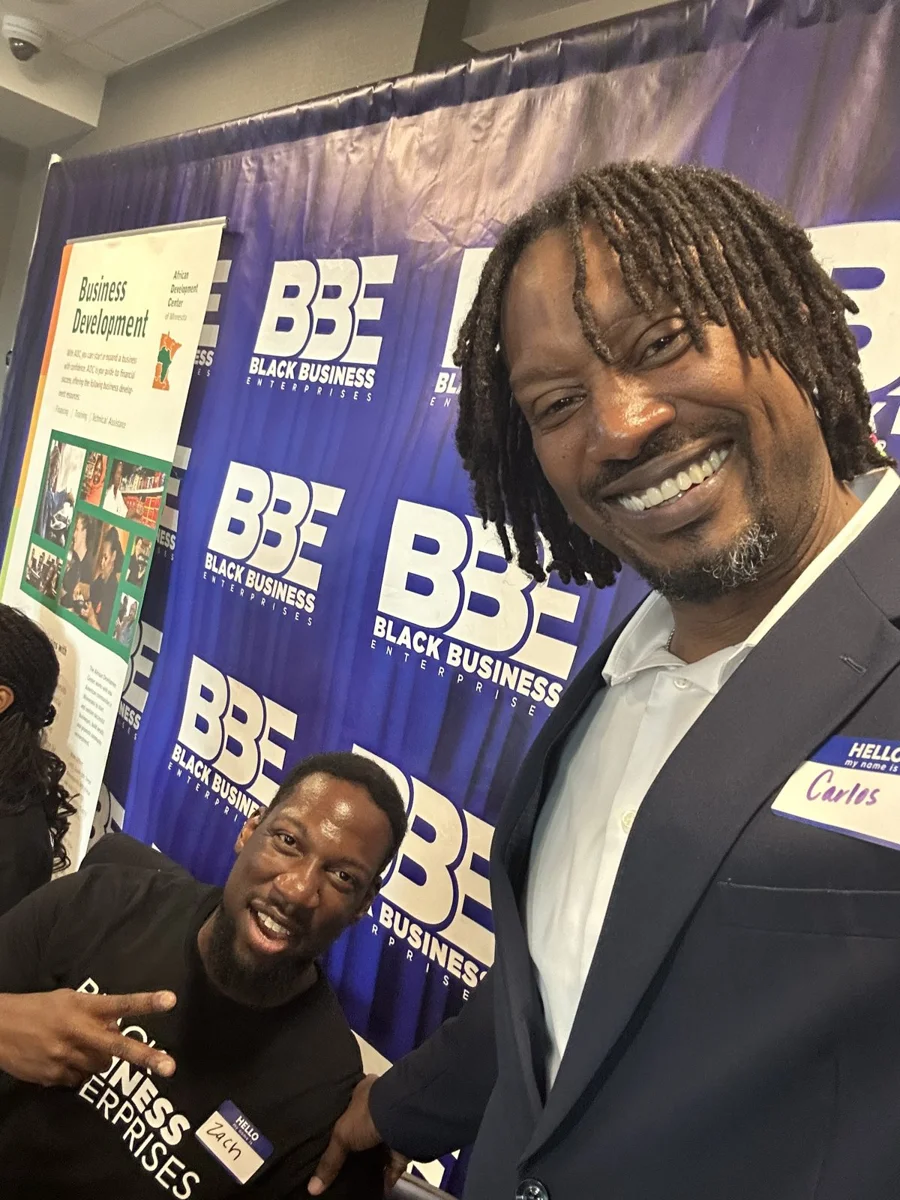
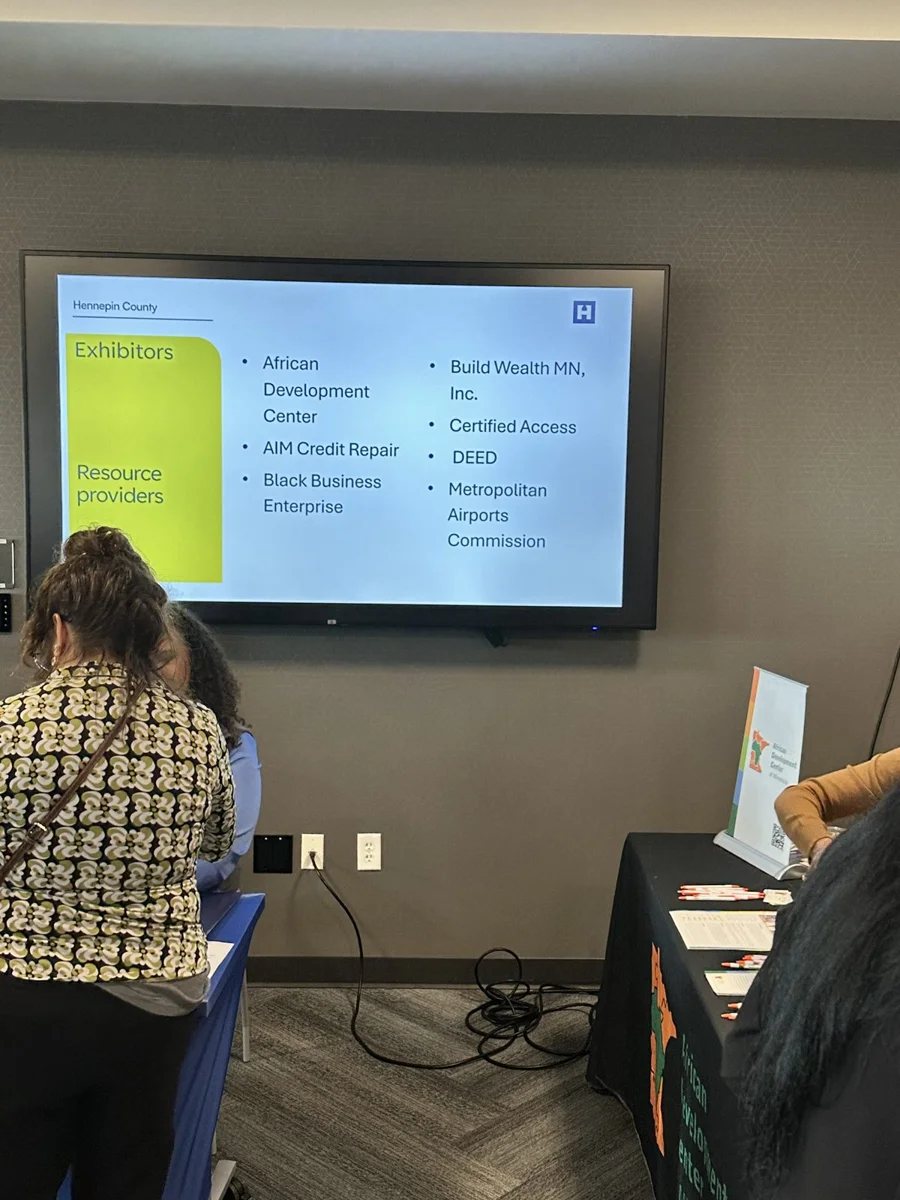
On October 28, our team spent the day at the 2026 Hennepin County Small Business Networking Event. AIM Credit Repair was proud to be listed as an exhibitor and resource provider, alongside organizations like the African Development Center, Black Business Enterprises, Build Wealth MN, Certified Access, DEED and the Metropolitan Airports Commission.
The room was full from start to finish. Contractors, consultants, service businesses and people with a brand-new idea all came looking for the same thing: the tools and connections to grow their business here in Minnesota.
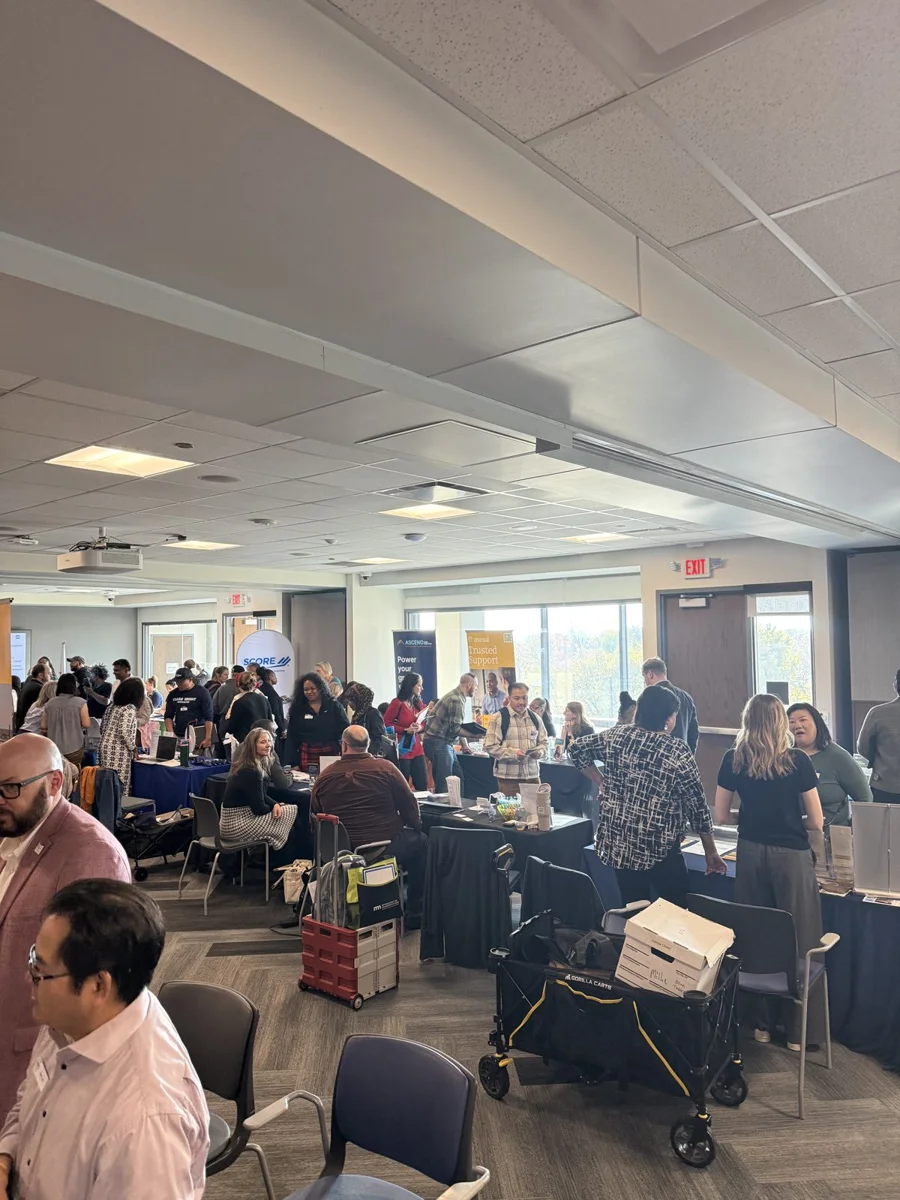
A big thank-you to Felicia Clomon, Small Business Relationship Manager, who planned the event and made it easy for every exhibitor to connect with the business owners who came through.
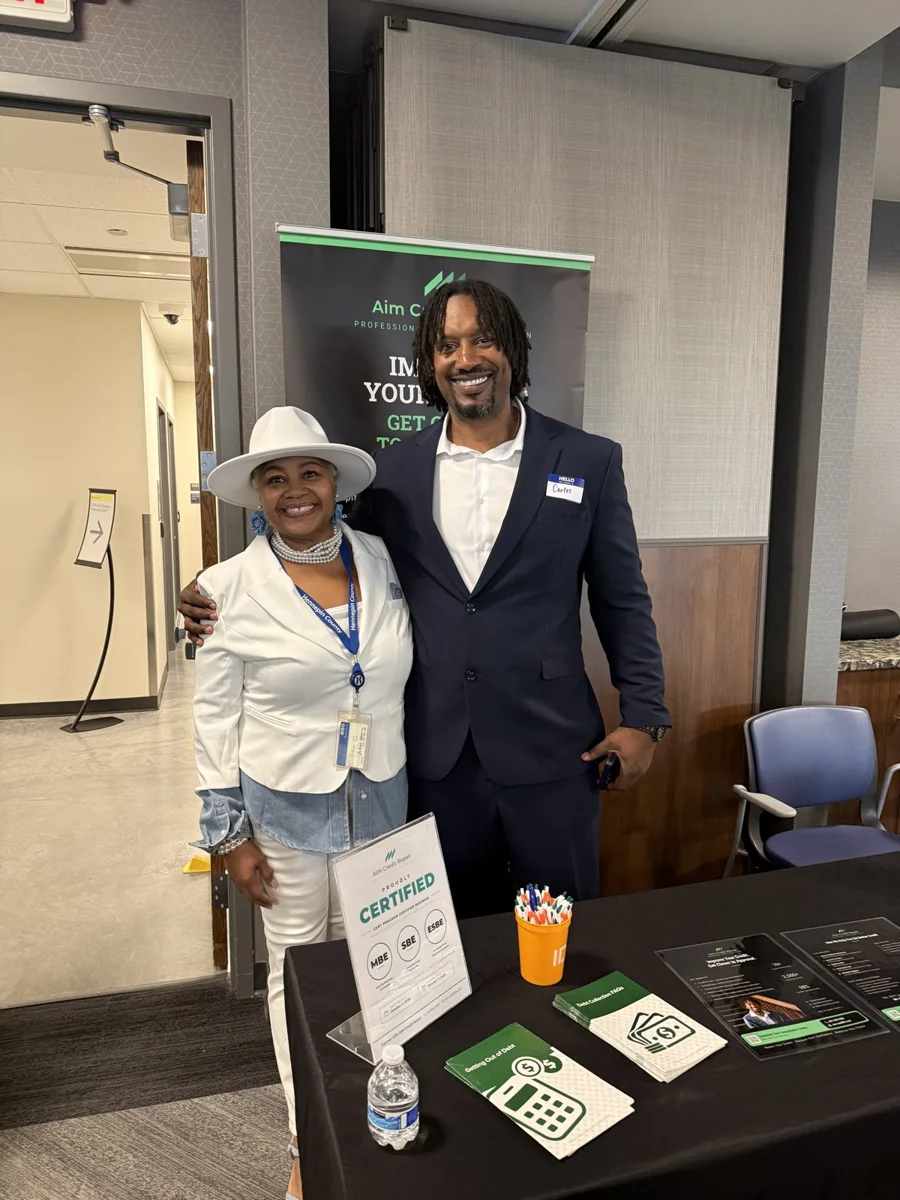
The Conversation I Kept Having
I talked with a lot of business owners that day, and one thing stood out more than anything else: too many small business owners are financing their business on their personal credit.
Personal credit cards for supplies. A personal loan to cover payroll. A personal car note for the work vehicle. It's understandable. When you're starting out, your personal credit is often the only credit you have. But over time, it creates real problems.
Your Personal Utilization Goes Up
High balances on personal cards can pull your personal scores down, even if you never miss a payment. Utilization—how much of your available credit you're using—is one of the biggest factors in your scores.
Your Business Never Builds Its Own History
If every purchase runs through you personally, the business has no track record when it's time to apply for real funding, whether that's an equipment loan, a line of credit or a contract that needs working capital.
Your Personal and Business Finances Get Tangled
That makes bookkeeping, taxes and lending decisions harder for everyone, including the lender reviewing your application.
The goal is a business that can stand on its own credit, so your personal credit isn't carrying the whole load.
Your Personal Credit Is Still the Foundation
Here's the honest part. When your business is new, many lenders will still look at your personal credit, and many business loans and credit lines ask for a personal guarantee. That means you're personally responsible if the business can't pay. So your personal credit matters, especially early on.
That's why the right order is:
- Get your personal credit in good shape.
- Build your business credit on purpose.
- Let the business carry more of its own financing over time.
If you're not sure where your personal credit stands, start with our guide to how credit repair works in Minnesota.
5 Steps to Start Building Business Credit in Minnesota
1. Know Where Your Personal Credit Stands
Pull your reports from Equifax, Experian and TransUnion for free at AnnualCreditReport.com. Look for accounts you don't recognize, wrong balances, inaccurate late payments and outdated collections. You have the right to dispute anything inaccurate yourself, for free. Our free dispute letter template walks you through it.
2. Set Your Business Up as Its Own Entity
Register your LLC or corporation with the Minnesota Secretary of State, get a free EIN from the IRS, and open a business bank account. Keep business and personal money separate from day one.
3. Make Your Business Look the Same Everywhere
Use the same business name, address and phone number on your registration, bank account, website and listings. Lenders and the business credit bureaus check that it all matches.
4. Get on the Business Credit Bureaus' Radar
Dun & Bradstreet, Experian Business and Equifax Business track business credit. Getting a D-U-N-S number from Dun & Bradstreet is a common first step, and it's free.
5. Use Accounts That Report, and Pay Early
Start with vendor accounts or a business credit card that reports to the business bureaus. Run business expenses through them, not your personal cards, and pay on time or early every time. That payment history is what builds your business profile.
Where AIM Fits In
Our work starts on the personal side. We review all three of your credit reports, identify information that's inaccurate, incomplete or outdated, and challenge it the right way with the bureaus and creditors. Then we help you build a plan so you're in a stronger position when you're ready to go after business funding.
Our office manager, Stephanie Hauer, was at the booth with me all day, and we're grateful to everyone who stopped by.
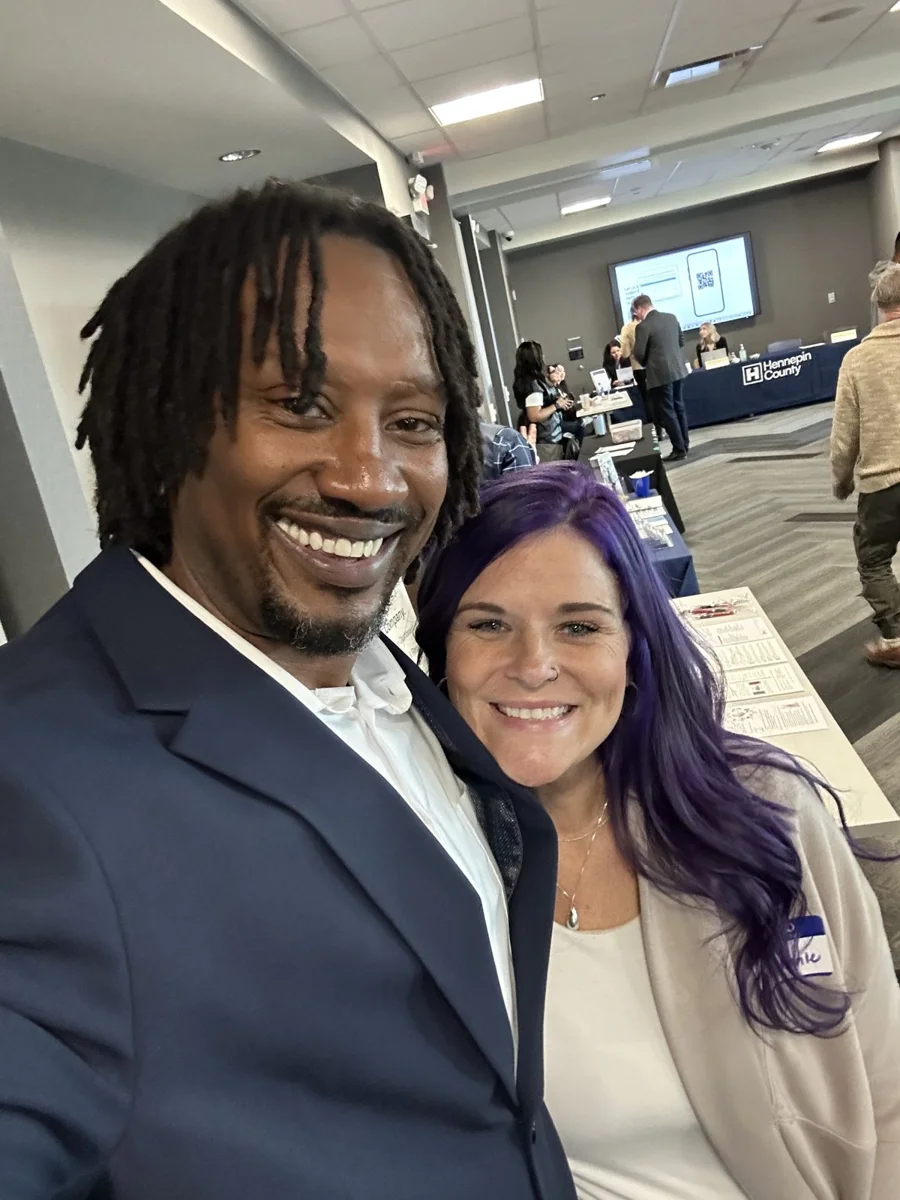
If you visited our table on October 28, thank you. It was great meeting you. If you didn't make it, you can still book a consultation, and we'll walk through where your credit stands and what your next steps could look like.
Frequently Asked Questions
Does My Personal Credit Affect My Business Credit?
When your business is new, often yes. Many lenders review the owner's personal credit, and many business loans and credit lines require a personal guarantee. As your business builds its own credit history, lenders can rely more on the business's profile.
How Do I Start Building Business Credit in Minnesota?
Register your business with the Minnesota Secretary of State, get a free EIN from the IRS, open a business bank account, get a D-U-N-S number from Dun & Bradstreet, and open vendor accounts or a business card that reports to the business credit bureaus. Pay on time or early.
Should I Use My Personal Credit Card for Business Expenses?
It's common when you're starting out, but over time it can raise your personal utilization and keeps your business from building its own history. Moving business expenses to accounts in the business's name helps separate the two.
Can AIM Credit Repair Help with Business Credit?
Our work focuses on your personal credit, which is the foundation lenders look at for most small businesses. We review all three of your reports, challenge information that's inaccurate, incomplete or outdated, and help you plan your next steps toward business funding. Results vary, and we don't guarantee specific outcomes.